Credit Score Mastery: Boost Your FICO Score by 50 Points
Anúncios
The pursuit of Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) remains a top priority for financially savvy individuals. This comprehensive guide, updated for 2026, delivers actionable insights and verified strategies. It focuses on immediate and impactful changes to elevate your FICO score.
Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) is now a more accessible goal for consumers looking to improve their financial standing. Recent analyses and expert recommendations underscore the importance of targeted interventions for significant score improvements. This article provides a clear roadmap, based on current financial best practices, to achieve a tangible FICO score increase.
Understanding the dynamics of your FICO score is the first step toward achieving financial empowerment. The strategies presented here are designed to be practical and effective, offering a direct path to an improved credit profile. By focusing on key areas, individuals can realistically aim for substantial gains within a six-month timeframe, impacting their access to credit and overall financial health.
The landscape of credit scoring evolves, and the 2026 edition of these steps reflects the latest methodologies and best practices. Adopting these strategies is not merely about increasing a number, but about unlocking better interest rates, loan approvals, and a stronger financial future. This guide is your essential resource for navigating the path to enhanced creditworthiness.
Understanding the FICO Score Landscape in 2026
The FICO score, a cornerstone of consumer credit evaluation, continues to be a critical determinant for financial opportunities in 2026. Its calculation, while complex, fundamentally relies on several key factors that influence lending decisions. A higher score opens doors to more favorable terms on loans and credit products.
Anúncios
Recent economic shifts and evolving lending practices mean that understanding the nuances of your FICO score is more important than ever. Lenders are increasingly scrutinizing credit reports with a focus on consistency and responsible financial behavior. This makes a proactive approach to credit management indispensable for consumers.
For those aiming for Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition), a foundational understanding of how FICO scores are generated is paramount. This knowledge empowers individuals to make informed decisions that directly impact their credit health. Focusing on the core components allows for strategic improvements rather than random efforts.
The Five Pillars of Your FICO Score
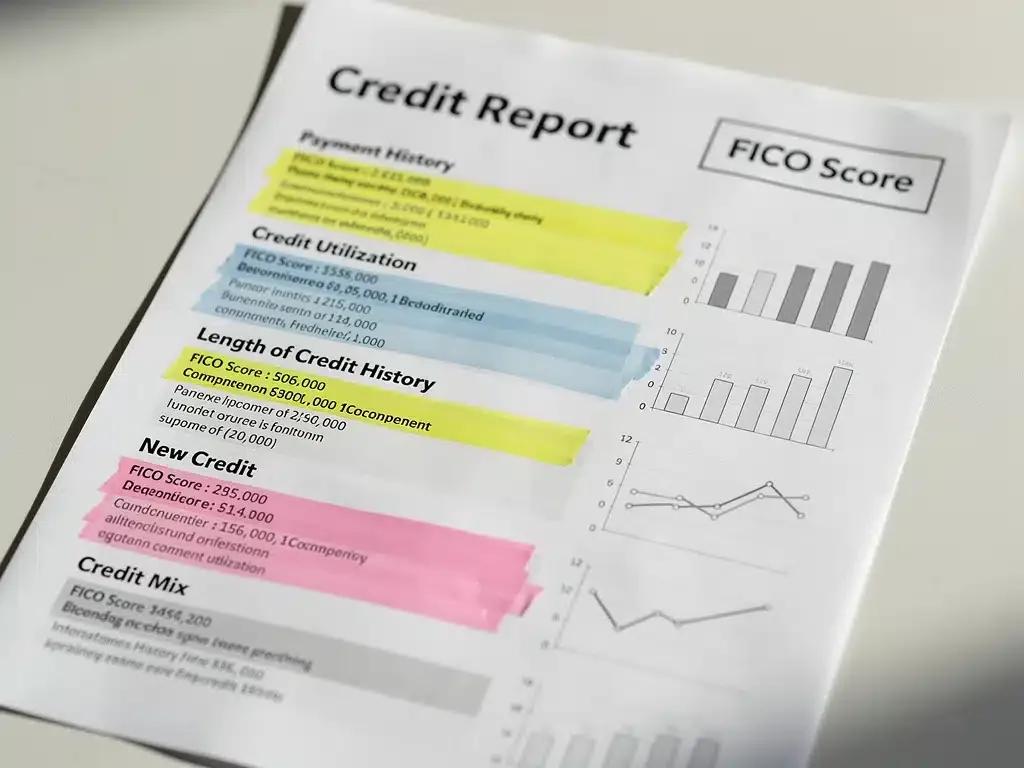
Your FICO score is composed of five main categories, each weighted differently in its calculation. Payment history holds the most significant weight, accounting for approximately 35% of your score. This emphasizes the critical importance of timely payments for all credit obligations.
Amounts owed, or credit utilization, makes up about 30% of your score, reflecting how much credit you are using compared to your available credit limits. Keeping this ratio low is a powerful strategy for credit improvement. The length of your credit history, contributing around 15%, rewards long-standing accounts and consistent usage.
New credit, at 10%, considers recent credit applications and newly opened accounts, which can temporarily lower your score due to hard inquiries. Finally, credit mix, also 10%, assesses the diversity of your credit accounts, such as installment loans and revolving credit. A balanced mix can positively influence your score.
Step 1: Optimize Payment History and Debt Management
The most direct and impactful way to achieve Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) is by meticulously managing your payment history. Late payments are a significant deterrent to a high FICO score, often causing substantial drops. Consistent on-time payments are the bedrock of good credit.
Beyond simply paying on time, strategically reducing your outstanding debt is crucial for improving your credit utilization ratio. This ratio compares the amount of credit you are using to the total credit available to you. A lower utilization percentage signals less risk to lenders and can quickly elevate your score.
Anúncios
Implementing a disciplined approach to debt repayment, especially on revolving accounts like credit cards, is non-negotiable. This step lays the groundwork for sustainable credit improvement and is often the fastest route to seeing positive changes in your FICO score. Focus on high-interest debts first to maximize impact.
Automate Payments to Avoid Missed Deadlines
One of the simplest yet most effective strategies is to set up automatic payments for all your credit accounts. This eliminates the risk of human error and ensures that minimum payments are always made on time, every time. Many creditors offer this service directly through their online portals.
While automating minimum payments prevents late marks, aim to pay more than the minimum whenever possible. This accelerates debt reduction and improves your credit utilization faster. Consider setting up reminders for larger payments or for when you plan to pay off larger chunks of debt.
Strategic Debt Reduction: The Avalanche or Snowball Method
To tackle existing debt, two popular methods are the debt avalanche and debt snowball. The avalanche method prioritizes paying off debts with the highest interest rates first, saving you money on interest over time. This approach is mathematically more efficient and can lead to quicker improvements in your credit utilization.
The debt snowball method focuses on paying off the smallest debts first, regardless of interest rate, providing psychological wins that can motivate continued effort. While less mathematically efficient, the psychological boost can be powerful for maintaining momentum. Choose the method that best suits your financial discipline and motivation.
- Prioritize paying down high-interest credit card balances immediately.
- Keep credit utilization below 30% across all accounts, ideally under 10%.
- Set up payment reminders or automatic deductions to prevent late payments.
- Review your credit report regularly for any discrepancies in payment history.
Step 2: Manage Credit Utilization and Credit Mix
Controlling your credit utilization ratio is a powerful lever for achieving Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition). This metric, representing the amount of credit you use versus your total available credit, significantly impacts your FICO score. Maintaining a low utilization rate signals responsible credit management to lenders.
Beyond just utilization, diversifying your credit portfolio, known as credit mix, also plays a role in your score. While less impactful than payment history or utilization, having a healthy mix of revolving credit (like credit cards) and installment loans (like mortgages or auto loans) can positively influence your FICO score. It demonstrates your ability to manage different types of credit responsibly.
Strategic management of both credit utilization and credit mix requires a proactive approach. It involves not just reducing debt but also understanding how your open accounts contribute to your overall credit profile. This holistic view is essential for anyone serious about improving their FICO score effectively within the six-month target.
Lowering Your Credit Utilization Ratio
To effectively lower your credit utilization, focus on two main strategies: paying down existing balances and, if appropriate, increasing your credit limits. Paying down balances is generally the more advisable and safer approach. Aim to pay off your credit card balances in full each month, or at least keep them well below 30% of your limit.
If you have multiple credit cards, spreading out your balances rather than maxing out one card can also help. However, the most effective method remains reducing the total amount you owe. Remember that your utilization is often reported to credit bureaus at the end of your billing cycle, so timing your payments can sometimes offer a temporary boost.
Strategizing Your Credit Mix
While you shouldn’t open new accounts solely to improve your credit mix, if you are already considering a new loan, understand its potential impact. A well-managed installment loan, such as a small personal loan, can add positively to your credit mix once established. However, be cautious; taking on unnecessary debt can quickly backfire.
The goal is a balanced portfolio that shows you can handle various credit types. For instance, if you only have credit cards, a secured loan or a small personal loan repaid diligently could enhance your credit mix over time. This aspect of Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) is about thoughtful, long-term planning.
- Keep individual credit card utilization below 30%, ideally 10% or less.
- Avoid closing old credit accounts, as this can reduce your total available credit and shorten your credit history.
- Consider a small, secured loan if you lack installment credit history, but only if you can manage it responsibly.
- Monitor your credit utilization regularly through free credit monitoring services.
Step 3: Monitor Your Credit Report and Dispute Errors
A crucial, often overlooked, step in achieving Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) involves vigilant monitoring of your credit report. Errors on your credit report are surprisingly common and can unfairly drag down your FICO score. Identifying and correcting these inaccuracies can provide an immediate and significant boost.
The Fair Credit Reporting Act (FCRA) grants you the right to access your credit reports from the three major bureaus—Equifax, Experian, and TransUnion—for free once every 12 months. Leveraging this right is essential for maintaining accuracy. Regular review ensures that all reported information is correct and reflective of your financial behavior.
Proactive monitoring and swift dispute resolution are not just about correcting past mistakes; they are about safeguarding your financial future. Even minor errors can have compounding effects, making it harder to secure favorable credit terms. This step empowers you to take control of your credit narrative.
Regularly Obtain and Review Your Credit Reports
Accessing your credit reports from AnnualCreditReport.com is the official, free method to obtain them. It is recommended to pull one report from a different bureau every four months. This staggered approach allows you to monitor your credit file throughout the year without cost, helping you catch errors or suspicious activity promptly.
When reviewing, pay close attention to personal information, account details, payment history, and any inquiries. Look for accounts you don’t recognize, incorrect payment statuses, or outdated negative information that should have been removed. These details can significantly impact your FICO score and require immediate action.
Effectively Dispute Inaccurate Information
If you find an error, you have the right to dispute it with both the credit bureau and the information provider (e.g., the lender). Gather all supporting documentation before initiating a dispute. Clearly explain the error and provide evidence to back up your claim. The credit bureaus are legally required to investigate your dispute within 30 days.
Keep detailed records of all communication, including dates, names, and copies of letters sent and received. Persistence is key; if an error is not resolved satisfactorily, follow up. Successfully removing negative, inaccurate entries can dramatically improve your FICO score, often by several points, aligning with the goals of Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition).
- Obtain your free credit reports from AnnualCreditReport.com at least once a year.
- Scrutinize every detail for inaccuracies, including account numbers, balances, and payment dates.
- Formally dispute any errors with both the credit bureau and the creditor, providing supporting documentation.
- Keep a meticulous record of all communications and outcomes related to your disputes.
Maintaining Positive Credit Habits Long-Term
Achieving a significant FICO score boost within six months is an impressive feat, but maintaining that progress requires consistent effort. The habits you cultivate during this intensive improvement period should ideally become permanent fixtures in your financial routine. Long-term credit health is built on a foundation of responsible and disciplined financial management.
Continuously applying the principles of timely payments, low credit utilization, and regular credit report monitoring will ensure your FICO score remains strong. These practices are not temporary fixes but essential components of a robust financial strategy. The benefits extend far beyond just a higher score, impacting various aspects of your financial life.
Embracing these positive credit habits as an ongoing lifestyle choice is the true essence of Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition). It’s about creating a sustainable framework for financial success that adapts to changing economic conditions and personal circumstances. This commitment yields lasting rewards.
The Role of Credit Age and New Accounts
As you work towards improving your FICO score, be mindful of your credit age. The length of your credit history contributes to your score, so avoid closing old, established accounts, even if they are paid off. These accounts demonstrate a long history of responsible credit usage, which is favorable to lenders.
Opening new credit accounts, especially too many in a short period, can temporarily lower your score due to hard inquiries and a reduction in your average credit age. While strategic new accounts can help with credit mix, exercise caution. Only open new credit when genuinely needed and after careful consideration of its impact on your overall credit profile.
Utilizing Credit Monitoring Services
Beyond the free annual reports, consider utilizing credit monitoring services. Many banks and credit card companies offer free credit score and report monitoring as a perk. These services can provide real-time alerts to significant changes in your credit file, such as new accounts being opened or inquiries made, helping you detect potential fraud or errors quickly.
These tools can be invaluable for maintaining your hard-earned FICO score. They offer peace of mind and an early warning system for any negative impacts, allowing you to take corrective action promptly. Consistent monitoring is a key component of long-term Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition).
Impact of a Higher FICO Score in 2026
Achieving a higher FICO score in 2026 transcends merely a numerical improvement; it unlocks a spectrum of enhanced financial opportunities. Lenders view individuals with stronger credit profiles as lower risk, which translates directly into more favorable borrowing terms. This can lead to substantial savings over the lifespan of various loans.
From securing a mortgage at a lower interest rate to qualifying for premium credit cards with attractive rewards programs, the benefits are tangible. A robust FICO score also plays a role in non-lending scenarios, such as renting an apartment, obtaining utility services, and even some employment background checks. Its influence is pervasive across your financial life.
For those who have committed to Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition), the rewards are often immediate and impactful. It signifies a transition from struggling with limited options to enjoying financial flexibility and greater purchasing power. This improved standing is a testament to diligent financial management.
Better Loan and Interest Rates
The most immediate and significant benefit of a higher FICO score is access to better interest rates on loans. Whether it’s a car loan, personal loan, or mortgage, even a small reduction in the interest rate can save thousands of dollars over the loan term. This directly impacts your monthly budget and overall financial burden.
For example, a difference of just half a percentage point on a 30-year mortgage can amount to tens of thousands in savings. Lenders reserve their best rates for borrowers with excellent credit, making a high FICO score a powerful negotiation tool. This financial advantage is a primary motivation for pursuing Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition).
Enhanced Access to Credit and Services
Beyond lower interest rates, a strong FICO score broadens your access to credit. This means you are more likely to be approved for loans and credit cards, and often with higher credit limits. This flexibility can be crucial for managing unexpected expenses or making significant investments without financial strain.
Furthermore, a good credit score can also influence non-lending decisions. Landlords often check credit scores for rental applications, and utility companies may waive security deposits for individuals with excellent credit. Some insurance providers also use credit-based insurance scores, which correlate with FICO scores, potentially leading to lower premiums. The ripple effect of strong credit is extensive.
Common Pitfalls to Avoid During Credit Improvement
While the path to Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) is clear, several common pitfalls can derail your progress. Being aware of these traps is just as important as knowing the right steps to take. Avoiding these mistakes will ensure your efforts are not wasted and your FICO score continues its upward trajectory.
One frequent error is applying for too much new credit in a short period. Each new application can result in a hard inquiry on your credit report, which can temporarily lower your score. While sometimes necessary, excessive applications signal higher risk to lenders and should be approached with caution, especially during an improvement phase.
Another significant pitfall is closing old credit accounts once they are paid off. While it might seem counterintuitive, closing an old account can negatively impact your credit utilization ratio and shorten your average credit history. Both factors can work against your goal of boosting your FICO score. Strategic account management is key.
Avoiding Excessive New Credit Applications
When you apply for new credit, lenders perform a ‘hard inquiry’ on your credit report. These inquiries remain on your report for two years and can slightly lower your score for a few months. While one or two inquiries won’t cause significant damage, a flurry of applications within a short timeframe suggests financial distress to lenders.
It’s advisable to only apply for credit when you truly need it and are confident in your approval chances. If you are rate shopping for a mortgage or auto loan, multiple inquiries within a short period (typically 14-45 days, depending on the scoring model) are often counted as a single inquiry, so group your applications within this window.
The Dangers of Closing Old Accounts
Closing an old credit card account, even one with a zero balance, can have a detrimental effect on your FICO score. Firstly, it reduces your total available credit, which can instantly increase your credit utilization ratio if you have balances on other cards. Secondly, it shortens the length of your credit history, which is a factor in your score calculation.
Unless an account carries an annual fee you can’t justify, or it’s an account you simply cannot trust yourself with, it’s generally better to keep old accounts open. Even if you don’t use them regularly, making a small purchase once every few months and paying it off immediately can keep the account active and contribute positively to your credit age and utilization.
- Refrain from applying for unnecessary new credit to avoid multiple hard inquiries.
- Do not close old, established credit accounts, as this can negatively impact credit age and utilization.
- Be wary of credit repair scams that promise quick fixes without addressing underlying issues.
- Understand that building credit takes time and consistent, responsible behavior.
| Key Action | Benefit for FICO Score |
|---|---|
| On-Time Payments | Improves payment history (35% of score), shows reliability. |
| Low Credit Utilization | Reduces amounts owed (30% of score), signals lower risk. |
| Dispute Credit Errors | Corrects negative entries, potentially boosting score quickly. |
| Maintain Old Accounts | Extends length of credit history (15% of score). |
Frequently Asked Questions About FICO Score Improvement
How quickly can I see results from these FICO Score Boost steps?▼While a 50-point boost in six months is an achievable goal, some changes can reflect faster. Reducing high credit card balances, for instance, often shows improvement within one to two billing cycles. Correcting credit report errors can also yield quick results once resolved, typically within 30-45 days after the dispute is filed.
Will checking my credit report lower my FICO score?▼No, checking your own credit report through services like AnnualCreditReport.com or your bank’s credit monitoring tools results in a ‘soft inquiry.’ Soft inquiries do not affect your FICO score. Only ‘hard inquiries’ from lenders when you apply for new credit can slightly lower your score temporarily, typically by a few points.
Is it better to pay off a credit card balance in full or just the minimum?▼Always aim to pay off your credit card balance in full each month. This not only saves you money on interest but also significantly improves your credit utilization ratio, which is a major factor in your FICO score. Paying only the minimum can lead to accumulating interest and slower credit score improvement.
What if I have old negative items on my credit report?▼Most negative items, such as late payments or collections, typically remain on your credit report for seven years, and bankruptcies for up to ten years. While you can dispute inaccuracies, legitimate negative items will remain until their reporting period ends. Over time, their impact lessens, especially as you establish new positive payment history.
Can secured credit cards help improve my FICO score?▼Yes, secured credit cards can be an excellent tool for rebuilding or establishing credit. They require a cash deposit as collateral, which often becomes your credit limit. By using the card responsibly and making on-time payments, the activity is reported to credit bureaus, helping you build positive payment history and improve your FICO score over time.
Looking Ahead: Sustaining Your FICO Score Mastery
The journey to Credit Score Mastery: 3 Actionable Steps to Boost Your FICO Score by 50 Points in 6 Months (2026 Edition) is not a one-time event but an ongoing commitment to financial health. The strategies outlined here provide a robust framework for initial improvement, yet their true value lies in their consistent application. As financial markets and personal circumstances evolve, so too must your approach to credit management.
Future developments in credit scoring models and lending regulations may introduce new considerations, making continuous education and adaptation essential. Staying informed about changes, particularly those that impact FICO score calculations, will allow you to maintain and further enhance your credit standing. This proactive stance is what separates short-term gains from lasting financial stability.
Ultimately, a strong FICO score is a powerful asset, offering flexibility and access to better financial products. By integrating these actionable steps into your regular financial routine, you are not just boosting a number; you are investing in a more secure and prosperous financial future. Your diligent efforts now will yield significant dividends for years to come.